How to Manage Digital Identity After Death
Digital identity after death does not disappear automatically. Credit reports, mail, social media profiles, subscriptions, cloud files, and financial accounts may remain active for months or years. Families must notify the right organizations, protect personal information, stop unnecessary charges, and preserve important records while respecting the person’s wishes and privacy.
What happens to online accounts after someone dies?
Most online accounts remain open until a family member, executor, account holder, or platform administrator takes action. Some services offer memorialization or deletion options, while others require proof of death and legal authority before releasing information.
This can create practical and emotional challenges. A deceased person may continue receiving bills, promotional messages, security alerts, and password-reset requests. Photos, messages, documents, and digital assets may also remain locked behind passwords or two-factor authentication.
The goal is not to access everything immediately. Families should first identify what exists, protect the person’s identity, preserve meaningful information, and close or transfer accounts according to the person’s wishes and applicable law.
Can a deceased person’s credit report still be used?
Yes. A credit file generally remains after death, and criminals may target it for identity theft. Someone could attempt to open credit, apply for services, or use personal information from public notices and social media.
A family member or authorized representative should contact the three major credit reporting agencies and request that the file be marked as belonging to a deceased person. The agencies may request a death certificate, identifying information, and documentation showing the requester’s authority.
Families should also:
- Review recent accounts and inquiries for suspicious activity.
- Notify banks, lenders, insurers, and credit-card companies.
- Watch for unfamiliar bills, collection notices, or account alerts.
- Keep copies of every letter, form, and confirmation number.
- Report suspected identity theft to the appropriate authorities.
Public information surrounding a death, including obituaries and social media posts, can sometimes provide scammers with information about someone who has recently died. That doesn't mean families should be afraid to tell their person's story. It does mean that protecting someone's identity deserves a place on the long list of things families consider after a death.
How should families handle mail after death?
Mail can reveal account numbers, medical information, insurance details, and financial obligations. It can also signal to criminals that a home may be vacant. Forwarding mail to a trusted representative helps families identify accounts and reduce exposure.
A representative can request mail forwarding through the postal service and update senders individually. Important items should be opened carefully, documented, and stored securely. Junk mail can be reduced over time, but families should avoid discarding financial or legal documents before reviewing them.
If the home is unoccupied, ask a trusted person to check it regularly. Secure packages, remove papers from outdoor areas, and consider changing mailbox access when appropriate.
What should happen to social media profiles?
Social media accounts require a thoughtful decision. Depending on the platform, families may be able to memorialize the profile, remove it, download certain information, or request deletion. Each service has its own process and may require a death certificate or proof of authority.
Memorialization can preserve photos and messages while limiting login activity. Deletion may better reflect the person’s wishes or protect private information. Before making a permanent decision, review any instructions in the person’s estate plan, password manager, or written digital legacy plan.
Avoid posting login credentials publicly or sharing more personal information than necessary. A memorial announcement should not include details that could help someone answer security questions.
A practical digital identity checklist
1. Gather essential documents
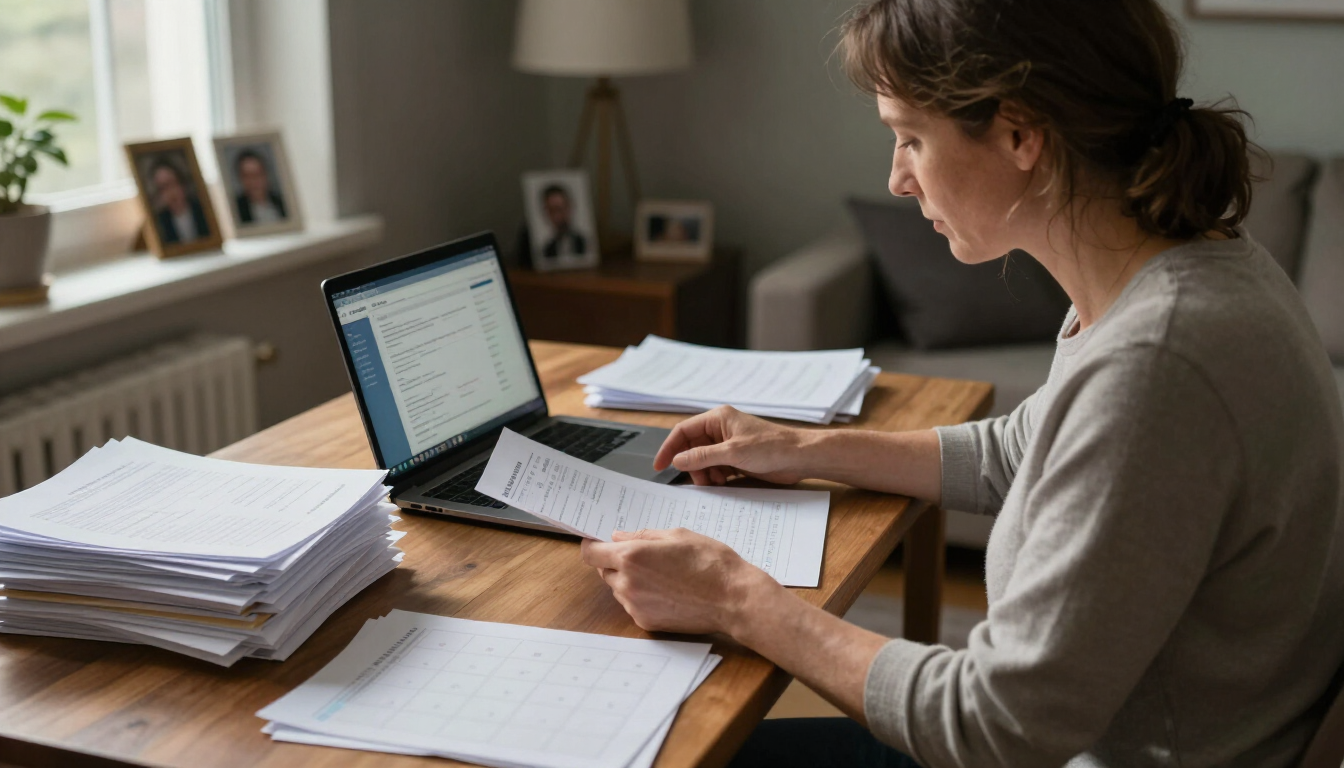
Collect several certified copies of the death certificate, the person’s identification, estate documents, insurance information, and contact details for the executor or authorized representative. Keep digital scans in a protected location, but do not email sensitive documents casually.
2. Create an account inventory
Look through paper mail, password managers, browser password storage, phones, computers, and bank statements. Record the organization, account type, contact method, action needed, and completion date.
Common categories include:
- Banking, credit cards, investments, and payment apps.
- Email, cloud storage, websites, and domain names.
- Social media, photo libraries, and streaming services.
- Utilities, memberships, apps, and recurring subscriptions.
- Insurance, pensions, benefits, unclaimed property, and digital assets.
Do not guess passwords repeatedly. Multiple failed attempts may lock an account or trigger security alerts.
3. Secure devices and information
Preserve phones, computers, tablets, external drives, and USB devices. Change the Wi-Fi password if needed, enable physical security, and avoid wiping a device before checking for records or instructions.
Ask the executor or attorney how to handle cryptocurrency, online businesses, monetized content, domain names, and intellectual property. These assets may have financial value and may require specialized assistance.
4. Stop unnecessary charges
Cancel subscriptions, memberships, automatic deliveries, and app payments that are no longer needed. Check bank and credit-card statements for recurring charges. Some contracts may need to remain active temporarily, such as utilities, insurance, storage, or property services.
Keep confirmation emails and cancellation numbers. If a company continues charging after proper notice, contact the financial institution and provide supporting records.
Finding forgotten assets and obligations
Digital accounts are not limited to social media. A person may have an old retirement account, life-insurance policy, tax refund, utility deposit, brokerage account, or unclaimed property. Search official state unclaimed-property databases and review employer, union, professional, and financial records.
Look for clues in:
- Email receipts and account-alert messages.
- Tax returns and annual financial statements.
- Banking applications and payment histories.
- Safe-deposit records and stored documents.
- Contact lists, calendars, and address books.
Families should be cautious with companies promising to recover money for an upfront fee. Verify the organization independently and avoid providing passwords or full financial details to an unsolicited caller.
How Into Our Kare supports families
One of the things we’ve learned is that taking care of someone after death involves a lot more than the funeral or cremation itself. Their mail keeps coming. Their online accounts remain open. Their social media is still there. Their credit file still exists. Bills and subscriptions may continue, and there may even be money or insurance policies the family doesn’t know about.
That’s why Into Our Kare provides the families we serve with access to specialized tools designed specifically to help with what comes after a death.
Families can use these tools to freeze their person’s credit, close or manage social media accounts, contact Social Security, cancel online accounts and subscriptions, cancel phone service, forward mail, search for unclaimed property, and even search for life insurance money that may be available to the family.
These aren’t things most people think about when making funeral arrangements. And frankly, why would they? When someone you love dies, nobody hands you a manual explaining every account, agency, subscription, credit bureau, and online service that now needs your attention.
We want to make that part a little more manageable.
For us, caring for someone doesn’t end when the funeral is over or when cremation takes place. There is still a family left behind with a lot to figure out. Giving them better tools to handle some of those loose ends is simply another part of what we mean by Kare.
Frequently asked questions
Should families delete a deceased person’s email account?
Not immediately. First determine whether the account contains bills, insurance information, account notices, family records, or instructions. After important information is preserved and relevant organizations are notified, the executor or authorized representative can request closure, forwarding, or deletion according to the provider’s policy.
Is it legal to access someone’s online accounts after death?
Access depends on the account agreement, local law, estate documents, and the person’s authorization. Having a password does not always grant permission to use an account. When in doubt, consult the executor, attorney, or service provider before logging in or downloading private information.
How long should families monitor accounts?
There is no universal timeline. Monitor financial statements, mail, credit activity, and important email accounts for several months, or longer when the estate is complex. Keep records until taxes, debts, insurance claims, and estate administration are complete.
Key takeaways
Digital identity after death requires deliberate, documented action. Accounts, credit files, mail, subscriptions, and social profiles can remain active and expose families to fraud, unnecessary expenses, or lost information. Start by securing documents and devices, notifying credit agencies and financial institutions, forwarding mail, reviewing recurring charges, and deciding what should be memorialized or deleted. Search for forgotten insurance, benefits, and unclaimed property, and ask for professional help when authority or privacy is unclear. If you need compassionate guidance alongside funeral arrangements, contact Into Our Kare or explore the planning resources available online.